Medicare Doesn't Cover Everything: Protect Your Gaps & Stay in Your Home
The biggest surprise for retirees is discovering that Medicare pays zero dollars for custodial long-term care or daily home living assistance. Supplemental benefits bridge these devastating gaps so you can preserve your retirement savings and age with dignity in your own home.
Official Medicare Gaps Under Federal Guidelines
Per Medicare.gov, Medicare only pays for medically necessary skilled care—leaving monumental non-medical financial burdens on you and your family.
Custodial & Home Care
Assistance with daily living activities (bathing, dressing, eating, meal prep, mobility). Medicare coverage: $0.
Long-Term Nursing Homes
Medicare only covers up to 100 days of skilled rehabilitation after a 3-day inpatient hospital stay. Ongoing nursing home stays are not covered.
Non-Medical Cancer Costs
Experimental immunotherapy travel, out-of-state lodging at premier cancer centers, and lost household income for family caregivers are never paid by Medicare.
Advantage Hospital Copays
Medicare Advantage plans frequently charge $350–$450 per day for the first 5 or 6 days in a hospital, creating unexpected multi-thousand dollar bills.
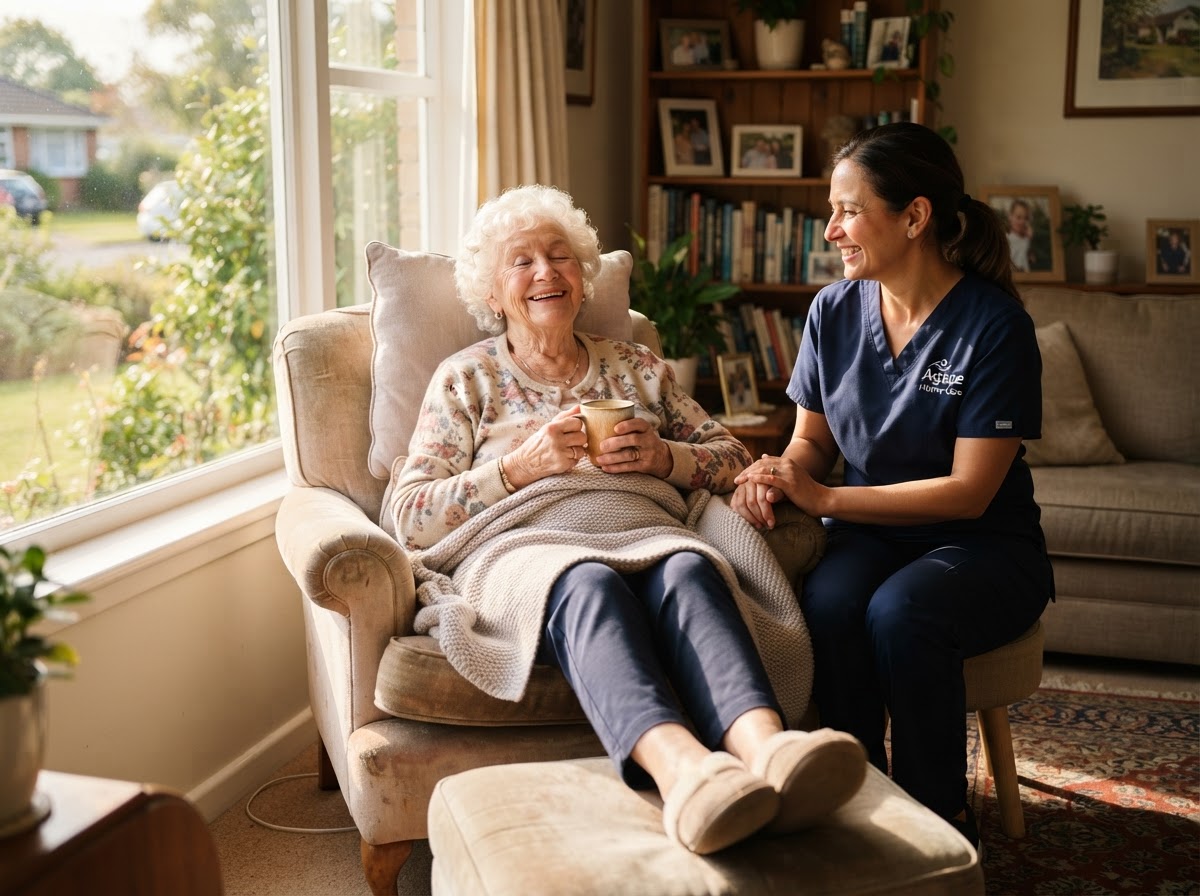
90% of Seniors Want to Age in Place
Short-Term Home Health Care insurance makes this financially feasible without draining family assets.
How Supplemental Home Care Plans Help You Stay in Your Own Home
Nobody wants to be forced into an institutional nursing facility simply because they need help with mobility, taking prescriptions, or light cooking. Modern Short-Term Home Health Care and Long-Term Care (LTC) plans empower you to receive dedicated professional care in the comfort of your living room.
Direct Daily Benefit for In-Home Caregivers
Policies pay a cash or indemnity daily benefit ($100–$400+/day) directly for licensed home health aides, certified nursing assistants, physical therapists, or companion care.
Relieving the Burden on Adult Children
Prevent your children from having to sacrifice their careers or personal savings to become full-time unassisted caregivers. Professional caregivers provide peace of mind for the whole family.
Protecting Nest Eggs from Medicaid Spend-Down
Nursing homes cost upwards of $100,000+ every single year. Without supplemental coverage, middle-class retirees often exhaust their entire life savings before qualifying for Medicaid poverty assistance.
Cancer, Heart Attack & Stroke Protection
When a catastrophic medical event strikes, having medical insurance is only half the battle. A critical illness policy pays a direct cash lump sum ($10,000 to $100,000+) directly to you upon diagnosis.
Paid Directly to You
The money goes straight to your bank account, not doctors or hospitals. Spend it however you need: mortgage payments, travel for specialized treatment, or home modifications.
Freedom of Experimental Care
If the newest breakthrough cancer therapy or clinical trial is denied by standard insurance, your lump-sum policy gives you the cash reserves to pursue it anyway.
Very Affordable in Your 60s
Because these policies target specific major triggers, premiums are remarkably affordable—often as low as $25 to $50 per month when secured in early retirement.
Hospital Indemnity Plans: Eliminate Advantage Inpatient Copays
If you choose a $0-premium Medicare Advantage plan, your largest financial risk is an unexpected hospital stay that charges $350/day for 5 days ($1,750 bill).
Let Us Build Your Custom Gap Protection Strategy
Every person has different health family history and retirement savings. Our licensed advisors evaluate your exact vulnerabilities and design a plan tailored to your budget.
Book Your Custom Gap Analysis