Clear, unbiased
Medicare Guidance tailored to your life.
Whether you are turning 65, working past 65 with employer benefits, or looking to protect against devastating medical and long-term care gaps, our licensed advisors help you make the right choice at zero cost to you.
Certified Medicare Assistance
We match you with the right path, not just any plan.
Original Medicare + Medigap vs Medicare Advantage compared side-by-side.
Turning 65 Roadmap
The critical 7-month Initial Enrollment Period (IEP), Social Security integration, and avoiding lifelong Part B & Part D late penalties.
Working Past Age 65
Stay on your group plan or transition? Understand the 20+ employee rule, HSA contribution freezes, and creditable prescription coverage.
Supplemental & Home Care
Cover catastrophic gaps Medicare never pays for: Cancer, Heart Attack/Stroke, and Long-Term Care plans that allow you to stay in your own home.
Original Medicare vs. Medicare Advantage
Almost all Medicare decisions boil down to two core paths. Here is how they stack up according to official Medicare.gov standards:
Original Medicare + Medigap + Part D
You receive Part A (Hospital) and Part B (Medical) from the federal government, pair it with a Medigap (Supplement) policy, and add a standalone prescription drug plan (Part D).
Medicare Advantage (Part C)
Private insurance companies approved by Medicare provide your Part A and Part B coverage, usually bundling prescription drugs (Part D), plus dental, vision, and gym perks.
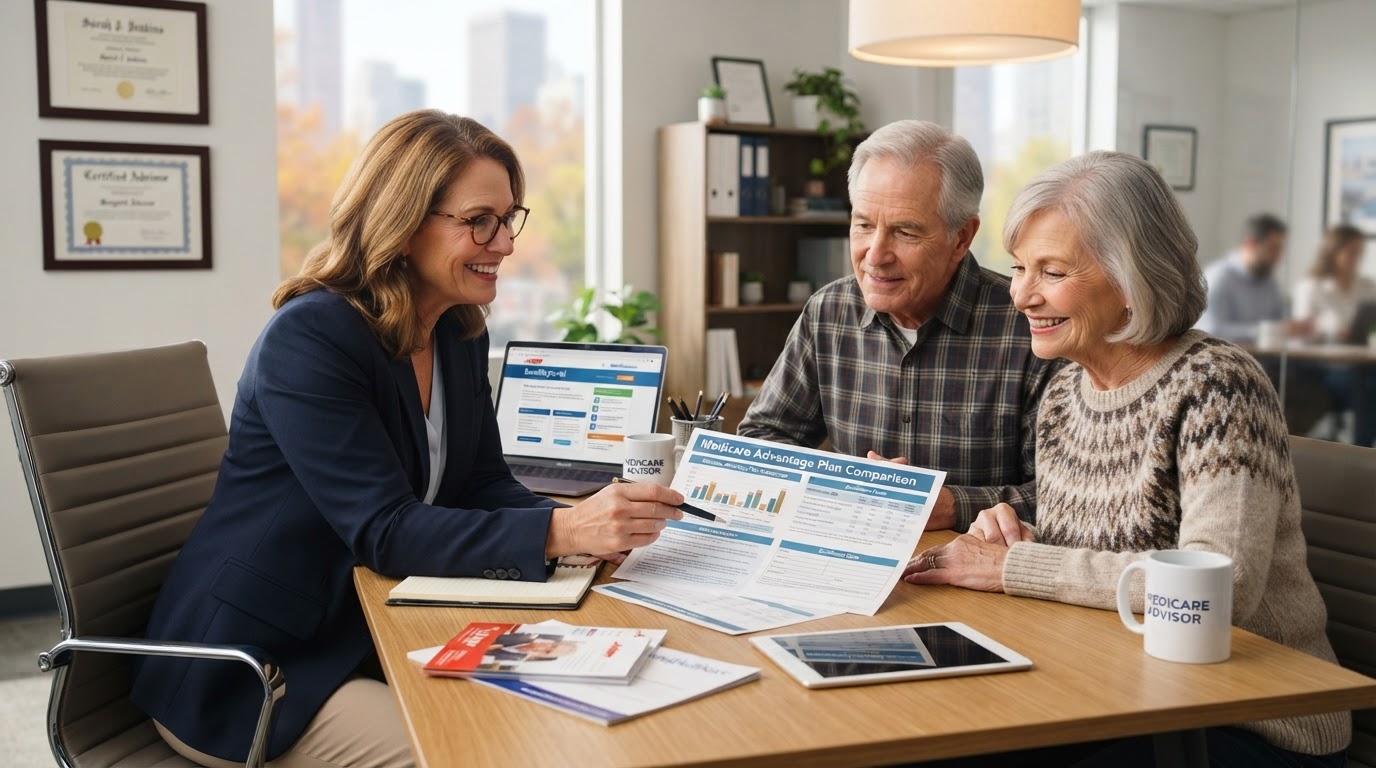
We represent your interests, not insurance carriers.
When you call an insurance company directly, you only hear about their products. As independent Medicare specialists, One Care Benefits Group reviews every major top-rated plan in your zip code.
We cross-reference every doctor you see and prescription you take against plan formularies before enrolling.
We don't disappear after enrollment. We help with claim issues, plan changes, and annual formulary reviews.
Specialized counseling on home care benefits so you never have to be forced into institutional nursing homes.
Rates are regulated by law. You pay the exact same price whether you use our service or try to navigate alone.
Missing an enrollment window can cost you permanently.
The federal government imposes permanent late-enrollment penalties for Part B (10% for every 12-month period you were eligible but didn’t sign up) and Part D (1% per month), which are added to your monthly bill for life. Don't guess—verify your timeline with our specialists.